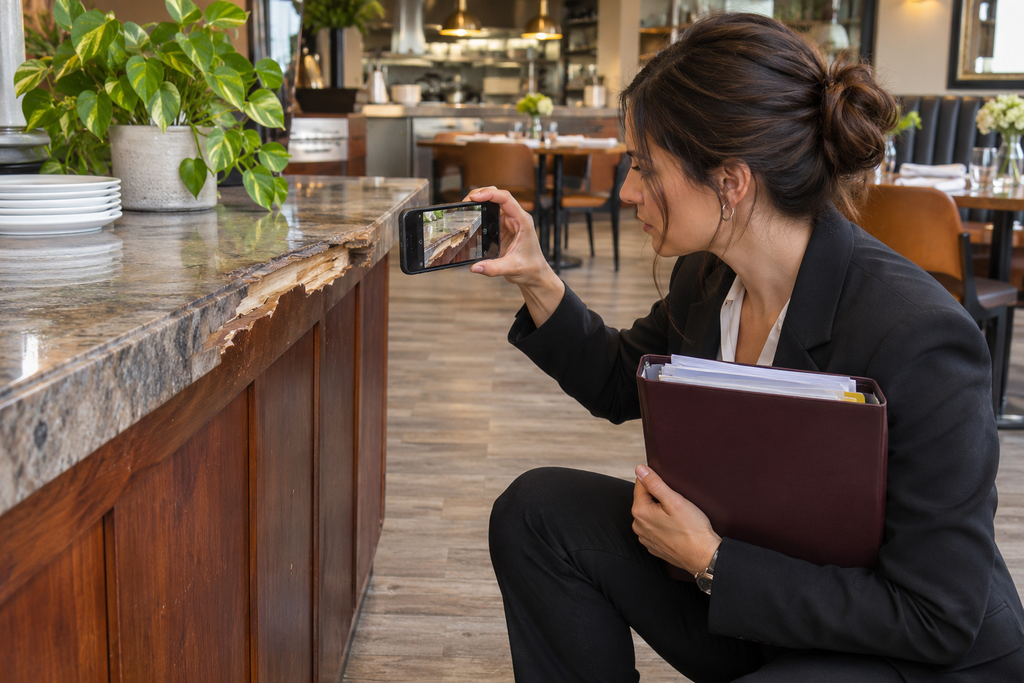
A useful business insurance claim record explains what happened, what was affected and what the business did next. For a restaurant, that can involve equipment, stock, customers, premises and trading income at the same time. Keeping those parts organized helps the insurer investigate and helps the owner manage recovery without relying on memory.
The process starts before a loss. Identify reporting contacts, decide who coordinates information and keep important records accessible outside the premises. The checklist below focuses on practical documentation for Ontario restaurant owners. Policy duties and instructions from the insurer still need to be followed for the particular claim.
Put immediate safety first
Obtain appropriate emergency assistance and follow applicable safety procedures. Do not enter an unsafe kitchen or attempt repairs simply to obtain photographs. Insurance evidence matters, but it should be collected only when the situation allows. Follow relevant reporting obligations separately from notifying the insurer.
Once safe, record the basic timeline: when the issue was discovered, who was present and what immediate measures were taken. Distinguish direct observations from information reported by another person. Avoid guessing the technical cause or assigning responsibility before the matter has been investigated.
Notify the insurer promptly
Use the current reporting instructions and provide an accurate initial description. Ask for the claim reference, contact details and next steps. You may not know the final loss amount yet; explain what is known and what remains uncertain rather than delaying notification until every invoice is available.
Ask about evidence preservation and approval requirements for urgent costs. Keep a record of advice received and who provided it. A broker can assist with reporting and communication, while the insurer assesses the claim under the wording. Do not assume notification alone confirms coverage.
Create separate sections for each loss component
Use folders for building or improvements, equipment, stock, interruption and relevant third-party matters. One incident can raise several insurance questions with different evidence and deductibles. Separating them makes the submission easier to understand than a single unexplained total.
Keep a master index showing documents supplied, dates and outstanding requests. Label provisional estimates clearly and retain originals. If a figure changes, explain the change rather than silently replacing the earlier version. A consistent record helps everyone follow how the reported loss developed.
Record damaged equipment accurately
List identifying details, ownership, location and available purchase or service records. Photograph damage when safe and retain qualified technical findings. Ask before disposing of damaged components or authorizing major non-emergency repairs, because inspection may be needed to establish cause and scope.
Separate repair estimates, replacement estimates and completed invoices. Record any financing or rental interests. The insurer may assess settlement using provisions different from the amount owed on a loan or the cost of a preferred upgrade, so keep the factual asset record distinct from the business’s purchasing decision.
Document stock quantities and values
Record what was affected, the quantity, location and relevant purchase information. For refrigerated goods, preserve appropriate temperature, alarm and service records where available. Follow food safety obligations and insurer instructions without treating reimbursement uncertainty as a reason to retain unsafe stock.
Clarify the valuation basis requested by the adjuster. Retail price, ingredient cost and the policy’s settlement basis can differ. Keep evidence of disposal where appropriate and avoid unsupported estimates presented as exact figures. Explain missing records honestly and discuss acceptable alternatives.
Keep financial disruption records separate
Business interruption may require sales reports, financial statements, payroll, expenses and evidence of saved costs or temporary trading. Ask which periods and formats are useful. A general fall in revenue does not automatically establish an insured interruption; the trigger and calculation need review.
Track continuing costs, additional recovery expenses and changes in operations separately. Record reduced hours, temporary menus and alternative premises with dates and reasons. Keep invoices and approvals for hired equipment or other measures so the financial effect can be explained using evidence rather than a later recollection.
Preserve customer incident facts
If someone alleges injury, illness or property damage, record their account accurately and notify the insurer under the reporting instructions. Preserve appropriate photographs, inspection records and footage lawfully. Keep sensitive information secure and collect only what is relevant to the incident.
Do not admit liability, promise a settlement or dismiss the allegation as impossible before review. Forward legal documents promptly. The manager’s job is to preserve facts and coordinate reporting, not to decide the final legal or insurance outcome during a busy service period.
Include contracts and ownership documents
A lease, equipment rental agreement or venue contract can help establish responsibilities. Supply the final relevant version rather than an early draft. Identify the legal businesses involved and the interests affected, particularly where the landlord, operator and equipment owner are different parties.
Do not assume another party’s insurance removes your reporting obligations. Ask how the insurers or responsible parties should be coordinated. Keep correspondence factual and preserve requests received from customers, contractors or landlords without making commitments beyond your authority.
Track decisions and outstanding requests
Agree who in the restaurant will coordinate documents and communicate with the adjuster. After important discussions, summarize requests, approvals and next milestones in writing. Ask specific questions about what remains needed rather than repeatedly asking for a final settlement date without context.
If progress is unclear, ask for the current position by claim component. Some items may be resolved while others remain under review. Your broker can help with communication, and the insurer can explain its formal review or complaint process if a concern remains unresolved.
Use a closing review after recovery
- Confirm which costs and components remain outstanding.
- Retain settlement information and related correspondence.
- Update inventories after replacement purchases.
- Record operational lessons and reporting improvements.
- Review limits, deductibles and recovery assumptions.
- Keep the claim history available for future insurance applications.
A clear file does not guarantee coverage or a particular settlement speed. It provides a reliable basis for assessment and business decisions. Review the record with the appropriate advisers and use what you learned to improve the restaurant’s emergency contacts, document storage and continuity planning before the next renewal.
Continue your coverage review
For the wider picture, read our hospitality insurance guide. Review How Long Does a Business Insurance Claim Take? A Restaurant Owner’s Timeline and Review Fire Insurance for Restaurants: Kitchen Damage, Cleanup and Reopening.
Explore Sterling’s restaurant insurance options or request a quote based on your operations.
General information only. Coverage depends on policy wording, exclusions, conditions and underwriting approval. Illustration generated for this article.